What's in this note
- Filing a home insurance claim: how the process actually works
- How a home insurance claim differs from a flood claim
- Before you start
- Step 1: Make sure everyone is safe and stop further damage
- What to photograph before you call your insurer
- Step 2: Document everything before you clean up
- Step 3: Review your policy and deductible before you call
- Where to find your own claim deadlines instead of trusting a number
- Step 4: Report the claim promptly and get a claim number
- The claim timeline: day 0 to day 30
- Step 5: Meet the adjuster and get your own repair estimates
- What the adjuster is actually assessing
- When a public adjuster is worth the fee
- Step 6: Understand how your payout is calculated
- What loss of use covers while you cannot live at home
- Step 7: Decide whether it is worth filing, then appeal a low offer
- A worked example: a wind and water claim through all seven steps
- Common mistakes that shrink a home insurance payout
- Troubleshooting: when the claim does not go smoothly
- Your home insurance claim checklist
- The bottom line
Short answer: To file a home insurance claim, stop the damage from spreading, photograph everything before any cleanup, report the loss to your insurer, meet the adjuster with your photos and inventory, then read the settlement, which pays covered damage minus depreciation and your deductible. First weigh whether a small claim that barely clears the deductible is worth the future premium cost, and treat a short first offer as a starting position you can dispute on paper.
Knowing how to file a home insurance claim well is mostly a matter of beating two clocks: the damage that keeps spreading while you stand there deciding what to do, and the record you will wish you had captured before the cleanup crew arrived. This walkthrough takes you from the first minutes after a storm, a burst pipe, or a fallen tree, through photographing, reporting, and meeting the adjuster, all the way to reading your settlement and disputing it if the offer comes up short.
By the end you will be able to run your own loss through all seven steps, know what a covered claim looks like after depreciation and your deductible, see which parts of the process reward speed, and know where the expensive mistakes hide. A home insurance claim is not the same animal as a flood claim, which runs on a separate policy with its own rules, so if outside water was involved, start with our flood-claim walkthrough instead. For the coverage picture behind all of this, our note on what home insurance actually covers is the companion piece, and you can pressure-test your own numbers with the companion below as you read.
Key takeaways
- The outcome: a documented claim that pays your covered damage reduced by depreciation and your deductible, with as little left on the table as possible and no surprises at settlement.
- The order that matters most: photograph everything before you clean up, because an adjuster who arrives days later can only value damage that can still be verified.
- The judgment call that saves money: a small claim that barely clears your deductible can cost more in future premium than it pays, so weigh whether to file at all.
- Replacement cost values the repair as new work and often holds depreciation back until repairs are finished; actual cash value pays the depreciated amount with nothing held back, so the basis on your policy shapes the check.
- A first offer is a starting position: if it looks short, you can supplement or appeal with your own estimates and photographs, and a disputed claim is argued on paper rather than on the phone.
Filing a home insurance claim: how the process actually works
Filing a home insurance claim is a documentation exercise wearing the costume of a phone call. Underneath the customer-service language, the insurer is answering three questions in order: did something sudden and accidental happen, does the policy respond to that particular cause, and what does it cost to put the property back. Everything you do from the moment the damage happens either helps answer those questions or leaves them open, and open questions get resolved conservatively. That is the whole logic of the seven steps below. One vocabulary note first: whether you call it filing a home insurance claim, filing a homeowners insurance claim, or claiming on your house insurance, you mean the same process. Home insurance and homeowners insurance are two names for one policy, and the claim runs identically under either label.
It helps to see the arc before you start walking it. A claim usually moves through five stages, and the labels differ by insurer but the shape rarely does:
- Protect. People first, then reasonable temporary measures that stop the loss from growing while you work out what to do.
- Record. Photographs, video, and a written inventory captured before anything is cleaned, moved, or thrown away.
- Report. Notice to the insurer, a claim number, an assigned adjuster, and a written list of what the insurer wants from you.
- Inspect. The adjuster's visit and estimate, alongside your own contractor estimates gathered independently.
- Settle. An offer, your review of it against your own numbers, payment, repairs, and any supplement or appeal.
The seven steps in this walkthrough map onto those five stages. Steps one and two are protect and record, step three is the reading you do before you speak to anyone, step four is report, step five is inspect, and steps six and seven are settle. Two of the seven are things most people skip: reading your own policy before you call, and deciding whether the loss is worth filing at all. Those two are where the money usually is. Set your own damage figure and deductible in the companion below before you read on, so the steps are attached to your numbers rather than to an abstract example.
One framing worth keeping: none of the deadlines, percentages, or dollar figures in this walkthrough are your policy’s. They are illustrative, chosen to show how the pieces fit. Your declarations page, your insurer, and your state department of insurance are the three places where the real numbers live, and this walkthrough points you at them repeatedly rather than pretending to replace them.
How a home insurance claim differs from a flood claim
Before the steps, hold one distinction in mind, because it decides which walkthrough you should even be reading. A home insurance claim and a flood claim look identical from the outside, both are water or weather on your floor, but they run on different policies with different rules. Homeowners insurance responds to sudden, accidental damage from causes such as wind, hail, fire, falling objects, and internal water such as a pipe bursting, all under one policy with, usually, a single deductible. Flood, meaning rising surface water that comes from outside the home, is excluded from standard homeowners policies and is covered only by a separate flood policy. Our water-damage coverage note walks that exact line between the internal water a homeowners policy responds to and the external flood it does not.
The practical consequences show up immediately. A homeowners claim typically applies one deductible to the whole loss, while a flood policy commonly applies separate deductibles to the building and to the contents. A homeowners policy often values the dwelling at replacement cost, while contents under a standard flood policy are commonly valued at depreciated actual cash value. And a homeowners policy generally includes coverage that helps with living costs during a covered rebuild, which a standard flood policy typically does not. Knowing which policy your loss falls under before you file means you record the right things, ask about the right deadlines, and expect the right shape of payout.
If you are not sure which one you are dealing with, the test is direction of travel: water that entered through a hole the storm made in your roof or wall is generally a homeowners question, while water that rose off the ground and came in at floor level is generally a flood question. Everything below assumes an ordinary homeowners loss. If the damage was flood, switch to the flood-claim walkthrough, and if you are working out whether you carry enough separate flood cover in the first place, our notes on how much flood insurance you need and what flood insurance costs sit alongside this one.
Before you start
This walkthrough assumes the immediate danger has passed and you are ready to work the claim. Gather these before you make the first call, because having them in hand turns a stressful process into a checklist:
- Your policy number and insurer contact. Find them on your declarations page, your insurer's app, or your latest renewal notice, along with the round-the-clock claims number. Our note on the home insurance declaration page shows what each line on that page is telling you.
- Your deductible. This single number decides whether the claim is even worth filing, so confirm it before you call. If you are not sure what it is or how it was set, start with what a deductible is and then our note on choosing your deductible.
- A charged phone or camera. Your entire claim rests on images taken before you clean up, so battery and storage come first, and cloud backup comes immediately after.
- A way to track receipts. A folder or a photo album on your phone for every dollar you spend on emergency protective work, drying, and temporary lodging.
- Any before photographs you already have. Older pictures of the rooms, from listing photos, family occasions, or an existing home inventory, are strong evidence of what the space looked like before the loss.
Time and difficulty: the active recording and reporting take an afternoon, but the full claim commonly runs from a few weeks to a few months from report to final payment, and a widespread storm that overloads the local adjusting network stretches that considerably. The work is not hard. It is just unforgiving about order. Record first, report promptly, keep everything, and read the offer carefully rather than depositing it on reflex.
Step 1: Make sure everyone is safe and stop further damage
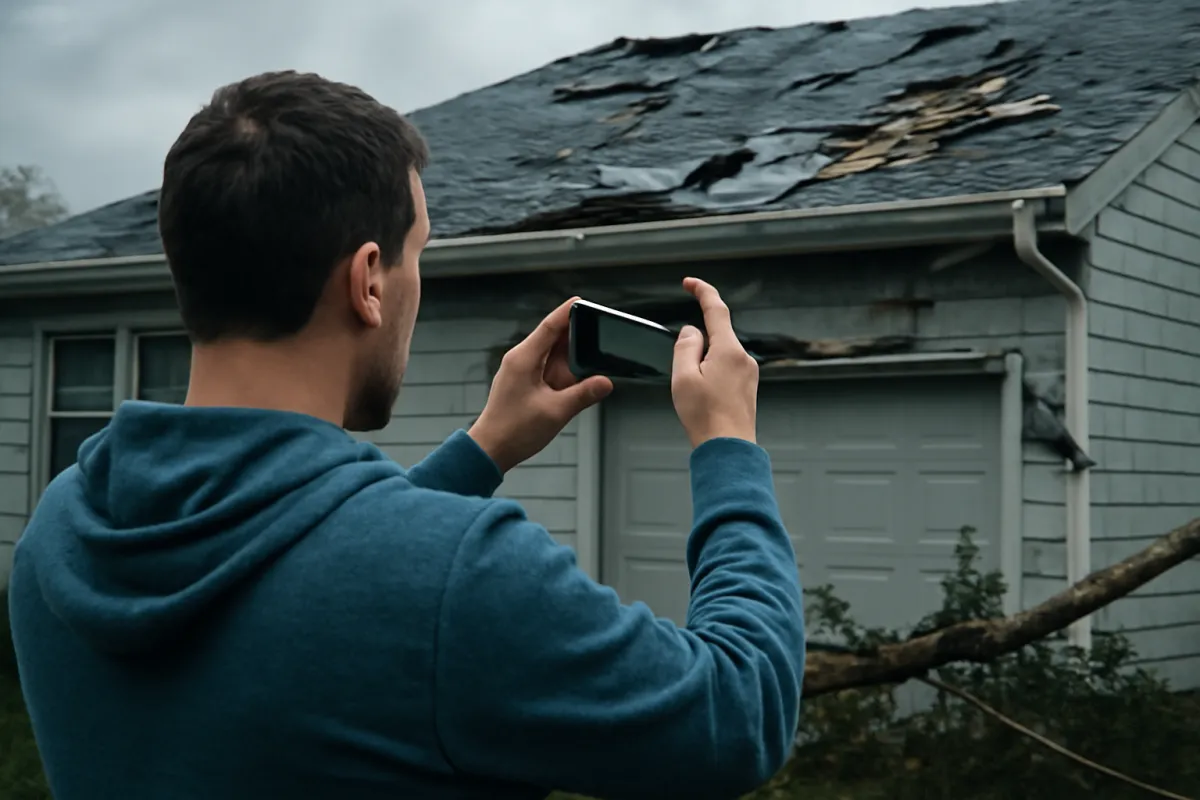
The first step is the one people skip in the rush to fix things, and skipping it costs the most. Before anything else, make sure people are safe and the structure is safe to be in. Storm damage hides downed power lines, gas leaks, weakened roof structures, broken glass, and standing water near outlets, so if there is any doubt, get everyone out and call the utility or the fire service rather than investigating yourself. Your health is not an insurance line item, and no photograph is worth a shock or a collapse.
Once people are safe, your job is to take reasonable steps to stop the damage from getting worse, because most policies ask you to. This duty to protect the property from further loss is standard language in homeowners policies: if a tree has opened the roof, cover it before the next rain; if a pipe has burst, shut the water off at the main; if a window is gone, board it. These are temporary protective measures, not permanent repairs, and their reasonable cost is commonly reimbursable as part of the claim on many policies, so keep every receipt and ask your insurer to confirm how yours treats them.
The watch-out is the boundary between protecting and repairing. You are expected to prevent further loss, but rebuilding the wall, replacing the roof, or hauling everything to the curb before the adjuster has seen it erases the evidence of scope and can reduce what gets paid. Cover it, dry it, shut it off, photograph what you did, and wait for the inspection before anything becomes permanent. If letting water sit allows mold or rot to spread over the following days, the insurer can treat that added damage as preventable, which our mold coverage note explains in more detail. Act promptly, but temporarily. Use the companion below to see the rough shape of the payout you are protecting.
What to photograph before you call your insurer
Between step one and step two sits a short, specific job: build the visual record. Most people photograph too little, photograph it too close, and photograph it after they have already moved things. Work the list below before you touch anything, and do it in this order.
- A wide shot of every affected room, taken from the doorway. This is the shot that establishes the space and lets every close-up be located within it. Adjusters and estimators read scope from these.
- Close shots of each specific point of damage. The stained ceiling, the buckled floorboards, the split window frame, the soaked drywall at the skirting. Get close enough that the damage is unmistakable.
- The exterior, all four elevations. Photograph the whole house from a distance on every side, then the specific exterior damage. Stay on the ground; nobody needs a roof photograph badly enough to climb after a storm.
- The point of entry, if you can see it safely. The opening in the roof, the broken window, the burst fitting. This is the image that ties the interior damage to a single sudden event rather than to gradual wear.
- Each significant damaged belonging, twice. Once in place in its room, once close enough to show the damage. Then capture the model and serial plate while it is still readable.
- Video, narrated, room by room. Walk each space slowly and say aloud what you are seeing and the date. Video captures context that stills miss and takes a fraction of the time.
- Whatever you had to do first. The tarp, the boarding, the shut-off valve, the fans. Photograph the protective work and its receipts, because that spending is part of the claim on many policies.
- Anything you have to discard for health or safety. If sodden carpet is already going moldy and has to go, photograph it thoroughly from several angles first, and keep a cut sample if you safely can.
Two habits make the difference. First, back everything up to the cloud before you do anything else, because a phone lost during a stressful week takes the claim with it. Second, keep the original full-resolution files rather than only the compressed versions you email, since detail is exactly what gets argued about later. If the loss came from a storm specifically, our walkthrough on documenting storm damage goes deeper into the weather-specific evidence, and our home inventory note covers building the contents record before you ever need it.
Step 2: Document everything before you clean up
Step one kept everyone safe and stopped the bleeding, and the photograph list above built the visual record. Step two turns that record into something an insurer can price. Alongside the images, build a written inventory: a running list of every damaged belonging with a short description, the approximate age, the brand or model where it matters, and a rough replacement value. Group it by room so nothing is forgotten. Keep the building damage, meaning the structure itself, on a separate list from the contents, because that is how a claim is usually organized and settled.
Precision here is worth real money, because contents are where payouts most often come in light. “Sofa, damaged” is an invitation for someone else to guess. “Three-seat fabric sofa, approximately six years old, water damage across both cushions and the base, replacement roughly 1,200 dollars, photographs 14 to 19” is a line an estimator can work with. Do the same for electronics, appliances, rugs, tools, and clothing. An illustrative loss might land at 28,000 dollars of structure damage and 8,000 dollars of contents, and only a specific, itemized list defends the contents half of that figure.
The watch-out is powerful and counterintuitive: the instinct to start pulling out soaked drywall and hauling ruined belongings to the curb right now is exactly what undermines a claim. Undocumented damage is effectively unpaid damage. Record first, then clean up. If something must go for health or safety reasons, photograph it thoroughly and keep a sample if you can do so safely. The more specific your record, the harder it is for a settlement to quietly shrink, and the companion below shows how the pieces of your loss are likely to split so you know which rooms to work hardest.
Step 3: Review your policy and deductible before you call
With the scene recorded, resist the urge to dial the claims line immediately and spend twenty minutes reading your own policy first, because that twenty minutes changes how you handle the entire claim. Pull up your declarations page and find four things: your deductible, your dwelling and contents limits, whether the policy values losses at replacement cost or actual cash value, and any coverage specific to your loss, including separate wind or hail deductibles and sub-limits on particular categories of belongings. Knowing these before you call means you speak the same language as the insurer and can tell whether an eventual offer is in the right range.
The single most important number is your deductible, because it decides whether the claim is worth filing. Your deductible comes off the top, so if the damage is only a little more than the deductible, you may recover very little while still putting a claim on your record. Say your damage is 3,000 dollars and your deductible is 2,500 dollars: filing recovers an illustrative 500 dollars and may affect your premium for years, which is rarely a good trade. Our note on choosing your deductible walks how that number gets set and why a higher deductible lowers your premium but raises exactly this threshold.
The watch-out is the settlement basis, because it is what surprises people at the check. On many replacement-cost policies the insurer values the loss at actual cash value first, pays that, and holds the depreciation back until the repairs are completed and documented, so a first check is intentionally smaller than the total. On an actual cash value policy there is nothing held back to recover. Read which basis applies to your dwelling and to your contents, since the two can differ, and confirm with your insurer how yours is administered rather than assuming. Then run your damage estimate, deductible, and settlement basis through the companion below before you call.
Where to find your own claim deadlines instead of trusting a number
Search for how long you have to file a home insurance claim and you will get confident numbers. Ignore them. The honest answer is that the timing on a home claim is governed by three separate things, none of which has a universal value, and all of which are written down somewhere you can actually check.
- The notice duty. Homeowners policies generally require you to tell the insurer about a loss without unreasonable delay. What counts as unreasonable is not a fixed count of days; it depends on the policy wording, the circumstances, and in some states on regulation. Reporting within a day or two makes the question moot.
- The documentation schedule. Once a claim is open, the insurer can ask you for a sworn statement of loss and supporting records, and the request itself carries the dates. Those dates come from your insurer in writing, on your claim, and they are the ones that matter to you.
- The limit on bringing suit. Policies commonly cap how long after a loss you can sue over the outcome. The cap varies by policy and by state, some states regulate the minimum, and it can keep running while you are negotiating informally.
So the move is not to memorise a number, it is to find yours. Open your policy to the section usually headed “Duties After Loss” or “Your Duties After a Loss” and read it; that is where the notice and documentation obligations are written. When you report the claim, ask the adjuster to confirm in writing what documentation is required and by when, and to tell you what limitation period the policy sets. Put every date on a calendar the day you receive it. Then check your state department of insurance, which publishes consumer information about claim-handling rules, including any prompt-payment or acknowledgement standards that apply to insurers in your state (the Washington State Office of the Insurance Commissioner’s claim tips for homeowners is one example).
The reason this walkthrough will not simply give you a figure is that a wrong deadline is worse than no deadline. A reader who trusts a number from a page that does not know their policy and misses their real one has been actively harmed by the reading. A reader who is pointed at their own policy, their own adjuster’s written confirmation, and their own state regulator ends up with dates that are actually true for them. That is a slower answer and a correct one.
Step 4: Report the claim promptly and get a claim number
With the scene recorded and your policy read, report the loss, and do it promptly. Call the claims number on your declarations page, use your insurer’s app, or call your agent, ideally within a day or two of the event. Prompt notice is both a practical advantage and a policy duty: waiting can give the insurer a reason to question the cause or to treat spreading damage as preventable. After a major storm the local adjusting network fills quickly, so early filers tend to be seen sooner. When you report, have your policy number ready, describe the cause and the date of loss, and give a rough scope of the damage.
This is the call where you lock down the facts that govern the rest of the process. Ask for and write down your claim number, then get the name, phone number, and email of the adjuster assigned to your file. Ask two direct questions and get the answers in writing: what documentation the insurer needs from you, and what dates apply to each item. Take notes on every conversation, including the date, the person, and what was said. A claim that later goes into dispute is reconstructed from exactly these notes, and the person with the contemporaneous record has an enormous advantage over the person working from memory.
The watch-out: be accurate but not speculative on that first call. Describe what happened and what you can see, but do not guess at causes you are unsure of, and do not commit to a damage figure before the full scope is recorded, because early numbers tend to move and the first one you say gets remembered. Do not let the phone call substitute for the written claim either; a verbal report opens the file, but the documentation still has to arrive. And think before you report a loss you may decide not to pursue, since in some systems even a reported claim that pays nothing can appear in your claims history. The companion below keeps a running estimate so the conversation is grounded in a real number.
The claim timeline: day 0 to day 30
Nobody can tell you how long your claim will take, and any page that promises a schedule is describing an imaginary insurer. What is useful is the rhythm: which part of the elapsed time is yours to control, and which part is spent waiting. The markers below are an illustrative sketch of an uncomplicated single-property claim, not a commitment, and a widespread catastrophe stretches every one of them.
- Day 0. Safety, temporary protective work, and the full photographic record. This is entirely in your hands and it is the part that determines what the rest of the claim can pay.
- Day 1 to day 3. Read your policy, finish the written inventory, decide whether to file, then report and get your claim number, your adjuster's details, and the insurer's written list of what it needs.
- Day 3 to day 14. The inspection window. The adjuster is scheduled and visits, you walk the property with them, and in parallel you gather your own contractor estimates so you have something to compare against rather than an offer arriving into a vacuum.
- Day 14 to day 30. The estimate is written and the offer arrives. You read it against your own numbers, ask about anything missing, and either accept, or assemble a supplement. Repairs begin, and on a replacement-cost policy any held-back depreciation is dealt with after the work is finished and documented.
Two things distort that sketch more than anything else. The first is catastrophe volume: after a regional storm, thousands of claims land at once, independent adjusters are brought in from out of state, and the inspection window alone can stretch well beyond anything above. The second is complexity, meaning disputed cause, hidden damage found mid-repair, or a large contents list. Neither is a reason to hurry your own documentation. Note the shape of the phases in the chart below: the front of the claim is short and decisive, and the back is long and mostly waiting.
Where the time goes in a home insurance claim
Illustrative shares of the elapsed time in the day 0 to day 30 sketch above: about 3 days recording and reporting, about 11 days to inspection, about 16 days to offer and settlement. Real claims vary widely and a catastrophe stretches the later phases most.
The three phases sum to 100 percent of the illustrative 30-day sketch: 3 days is 10 percent, 11 days is about 37 percent, and 16 days is about 53 percent. The short front phase is the one you control, and everything the later phases can pay depends on what you recorded in it.
Step 5: Meet the adjuster and get your own repair estimates
The adjuster visit is the hinge of the whole claim. The insurer assigns an adjuster to inspect the damage, and it helps to remember who pays them: the adjuster represents the insurance company, not you, which does not make them an adversary but does mean their estimate reflects the insurer’s scope assumptions and pricing data. When they arrive, walk the property with them, hand over your photographs, video, and itemized inventory, and point out damage that is not obvious, including water behind cabinets, under flooring, inside the attic, and along the roofline. The more you surface during the visit, the more complete the estimate. If you disagree with something on the spot, say so and note it.
Here is the move most homeowners skip: get your own written repair estimates from licensed contractors, independent of the adjuster. This is the most reliable way to check whether the insurer’s number covers the real scope and the real cost of the work in your area. If your contractor prices the roof and interior repairs at an illustrative 30,000 dollars while the adjuster’s estimate lands at 25,500 dollars, that 4,500 dollar gap is not a complaint, it is a documented basis for a supplement. Ask your contractor for a line-item estimate rather than a single total, because a lump sum cannot be compared against anything.
The watch-out: do not sign anything that locks you to a specific contractor or assigns your claim benefits away before you understand it, and be cautious of anyone who knocks on your door after a storm promising a free roof in exchange for a signature. A legitimate contractor gives you an estimate, not a contract that captures your insurance payment. Verify a licence before you sign, and read anything described as a routine formality twice. Compare your contractor estimates against the illustrative payout in the companion below to see whether the offer covers the work.
What the adjuster is actually assessing
It is easier to prepare for the inspection once you know what is being decided during it. An adjuster is not simply totalling visible damage. They are building a file that answers several separate questions, and each one is a place where your documentation either helps or is silent.
- Cause. What happened, and was it sudden and accidental or gradual? This is the single biggest determinant of whether anything gets paid, and it is why the photograph of the point of entry matters so much.
- Coverage fit. Which part of the policy responds, if any. Structure, contents, other structures such as a detached garage, and living expenses are separate buckets with separate limits.
- Scope. What has to be done to repair it, listed as tasks rather than as a total. Scope disputes, meaning the adjuster's list is shorter than reality, are the most common source of a low offer.
- Quantity. Measurements. Square footage of flooring, linear feet of skirting, roof squares, ceiling area. If a measurement is short, everything priced off it is short.
- Price. Unit costs for labor and materials, usually from estimating software with regional pricing. This is where a local contractor estimate can legitimately differ.
- Condition and age. How old the damaged item or building component was, which drives the depreciation applied to reach actual cash value.
- Pre-existing damage. Anything that looks like it predates the event. Old photographs of the same space are the strongest possible answer here.
Read your own file through that list before the visit and you will spot the gaps. Do you have an image that establishes cause, or only images of the aftermath? Have you separated structure from contents so the coverage buckets are obvious? Do you have anything at all showing the condition of the roof or the floor before the event? You do not have to argue any of these points during the inspection. You just have to make sure the evidence exists, because an assessment can only work from what is in front of it. If the loss involved someone else being hurt on your property, that runs through a different part of the policy entirely, which our note on personal liability coverage covers.
When a public adjuster is worth the fee
A public adjuster is a licensed professional who works for the policyholder rather than for the insurance company. They document the loss, prepare their own scope and estimate, and negotiate the claim on your behalf. They are regulated at state level, they must be licensed in the state where the loss happened, and they are typically paid a percentage of the settlement under a written contract. That percentage is set by the contract and, in several states, capped by regulation, so the number is a matter for your contract and your state’s rules rather than something anyone can quote you generically.
The case for hiring one strengthens with the size and complexity of the loss. A large structural claim, a total loss, a claim where the insurer and your contractor disagree about cause rather than price, or a claim you simply do not have the time or health to work yourself are the situations where the fee can be worth it. The case weakens sharply on a small, clean claim: paying a percentage of a modest settlement to have someone submit documentation you could have submitted yourself is rarely good value, and on a small loss the fee can eat most of what you gain.
Before signing anything, verify the licence directly with your state department of insurance, read the contract for the fee basis and how to terminate it, and be clear about whether the percentage applies to the whole settlement or only to amounts recovered above the insurer’s existing offer. Be skeptical of anyone soliciting door to door immediately after a storm; several states regulate exactly that behaviour. Our note comparing a public adjuster with the insurance company’s adjuster sets out who each one answers to and where the incentives sit.
Step 6: Understand how your payout is calculated
When the offer arrives, read it as a short stack of levers rather than one number, because that is how it was built. Start with the covered damage, meaning the cost to repair or replace everything the policy responds to, split between the structure and your contents. From there, two things reduce it before you see a dollar: depreciation and your deductible. Understanding both is what lets you tell a reasonable offer from a light one, and it is why two people with identical damage can receive very different checks.
Depreciation is the larger of the two. On a replacement-cost policy the insurer typically works out the full replacement cost, subtracts depreciation for age and wear to reach the actual cash value, pays that amount, and then addresses the held-back depreciation once repairs are completed and documented. So a first check that looks light is often not the final number: it is the actual cash value payment. On an actual cash value policy there is no held-back portion to recover, so the smaller amount is the whole amount. This is the exact mechanism our replacement cost versus actual cash value note breaks down, and it is why the basis on your declarations page matters so much. How the recovery is administered, and what documentation triggers it, is a question for your policy and your insurer rather than a universal rule.
Put together on an illustrative loss: suppose 28,000 dollars of structure damage and 8,000 dollars of contents damage, so 36,000 dollars in total, on a replacement-cost policy with a 2,000 dollar deductible. Say an illustrative 6,000 dollars of depreciation is applied to the structure, bringing it from 28,000 down to an actual cash value of 22,000. The deductible comes off, leaving 20,000 for the structure, and the 8,000 of contents is paid alongside it, so the first payment is an illustrative 28,000 dollars. The 6,000 of depreciation is addressed after the repairs are completed and documented, bringing the illustrative total to 34,000, with the 2,000 deductible absorbed by you. The watch-out: do not treat the first check as the whole claim, and do not spend the held-back portion before the work that recovers it is done. Run your own figures through the companion below.
Where a home insurance claim payout goes
An illustrative 36,000 dollar wind and water loss: 28,000 in structure damage and 8,000 in contents, on a replacement-cost policy with a 2,000 dollar deductible and 6,000 dollars of depreciation held back until repairs are documented. Your policy, insurer, and state can move every figure.
Bars are scaled to the ~$20,000 up-front structure figure, so 8,000 is 40 percent of it, 6,000 is 30 percent, and 2,000 is 10 percent. The four slices sum to the full 36,000 dollar loss: 20,000 plus 8,000 paid up front, 6,000 addressed once repairs are documented, and 2,000 absorbed as the deductible. Switching the companion to an actual cash value basis applies a heavier illustrative haircut, because on that basis contents depreciate too and nothing is held back to recover.
What loss of use covers while you cannot live at home
One part of a homeowners policy goes almost unmentioned until the day it matters, and then it is the difference between a hard month and an impossible one. Loss of use, often labelled additional living expenses or Coverage D on a declarations page, is the part that helps with the cost of living somewhere else while a covered loss makes your home unfit to live in. It is a separate bucket from the structure and contents limits, with its own limit and often its own time restriction, and it is claimed separately from the repair.
The mechanism catches people out, so it is worth stating plainly. Loss of use is generally written to cover the increase in your living costs, not the whole of them. If you were already paying a mortgage and buying groceries, those costs did not appear because of the fire; what appeared is the hotel bill, the short-term rental, the extra distance you now drive, the laundry you cannot do at home, the meals you cannot cook. That increase is what the coverage is aimed at. Exactly how your insurer applies it, what it needs to see, and what limit and time restriction apply are all questions for your declarations page and your adjuster.
The practical consequence is a receipts problem. Keep everything from the first night: hotel folios, rental agreements, restaurant receipts, fuel, laundry, pet boarding, storage. Log the dates you were out of the home. Ask the adjuster early, in writing, what the limit is, whether there is a time restriction, and what documentation is expected, because this is the coverage most likely to be under-claimed simply because nobody kept the paperwork. If you are working out whether your overall limits are the right size, our note on how much home insurance you need covers how the buckets relate, and dwelling coverage explains the largest one.
Step 7: Decide whether it is worth filing, then appeal a low offer
Not every loss should become a claim, and knowing when to skip the filing is one of the most valuable skills a policyholder has. Insurers price partly on claim history, so a paid claim can affect your renewal premium and remain visible to insurers for some years through shared claims reporting, which means a small claim can cost more over time than it pays. The rough test many people use: if the damage is not much more than your deductible, paying out of pocket often beats filing (the Washington State Office of the Insurance Commissioner’s claim-filing page offers the same test). Our note on how a claim can affect your premium walks that tradeoff, and every figure in it is illustrative rather than a quote. Large losses, structural damage, and anything involving injury to another person sit in a different category and are almost always worth reporting.
If you do file and the offer comes up short, treat it as a starting position rather than a verdict. Work out why by comparing the adjuster’s estimate line by line against your own contractor estimates and your record. The gap usually sits in one of a few places: a repair scope narrower than the real damage, a cause attributed to wear or neglect rather than a sudden event, measurements that are short, materials or labor priced below your local rates, or depreciation applied more heavily than the age of the item suggests. Naming the specific disagreement is what turns a vague complaint into a supplement someone can act on.
The mechanics: put your disagreement in writing, attach the evidence, meaning contractor bids, photographs, receipts, and an itemized rebuttal, and submit it as a supplement or a formal appeal. Keep copies of everything, because a disputed claim is argued on paper. Our walkthrough on appealing a denied claim sets out that process step by step. If you believe the claim is being handled unfairly, your state department of insurance takes consumer complaints (for example, the Texas Department of Insurance’s complaint page or Washington’s insurance commissioner complaint page), and for a large or complex loss a licensed public adjuster or an attorney experienced in coverage disputes can be worth the fee. Ask, in writing, what deadlines apply to your dispute and whether accepting a payment affects your ability to seek more, before you deposit anything. Weigh the companion’s worth-filing note against your deductible before you commit either way.
A worked example: a wind and water claim through all seven steps
Walk one illustrative home through the whole process. During a summer windstorm, gusts tear a section of shingles off the roof of the Navarro home, and rain gets in overnight, soaking the ceiling and drywall in two upstairs rooms, buckling the hardwood floor, and ruining a rug, a sofa, and some electronics. By morning the wind has passed, leaving a torn roof, stained ceilings, warped floors, and damaged belongings. The Navarros carry a replacement-cost homeowners policy with a 2,000 dollar deductible.
Step one: they confirm nobody is hurt and no wires are down, then cover the roof and set out buckets and fans to stop more water spreading, keeping the receipts for the tarp and plywood. Step two: before touching the interior, they photograph and video every damaged room, the torn roof from the ground, the water line on the ceilings, and each ruined belonging, then build a room-by-room inventory with ages and rough values, keeping the structure list separate from the contents. Step three: they pull the declarations page, confirm the 2,000 dollar deductible and that both dwelling and contents are written at replacement cost, and read the duties-after-loss section. Step four: that same day they call the claims line, get a claim number, write down the adjuster’s contact details, and ask for the documentation requirements and dates in writing.
Step five: the adjuster inspects, agrees the damage is wind driven, and writes an estimate, while the Navarros get their own roofing and interior contractor estimates to compare line by line. Step six: the covered damage lands at an illustrative 28,000 dollars for the structure and 8,000 dollars for contents, so 36,000 dollars in total. An illustrative 6,000 dollars of depreciation is applied to the structure, bringing it to 22,000; the 2,000 dollar deductible comes off, leaving 20,000; the 8,000 of contents is paid alongside it, so the first payment is 28,000 dollars. The 6,000 of held-back depreciation is addressed after the roof and the rooms are repaired and the receipts are submitted, taking the illustrative total to 34,000 dollars, with the Navarros absorbing the 2,000 dollar deductible.
Step seven: because this is a large loss well above the deductible, filing is clearly worth it. When their contractor finds additional water damage behind a wall after the first payment, they do not assume the offer was final; they submit a supplement with new photographs and a revised line-item estimate. They also claim the hotel nights from the two days the upstairs was unusable, having kept the folios. Same storm, a clean recovery, because the order and the record were respected. Set your own damage figure, deductible, and settlement basis in the companion below to see your version of this walkthrough.
Common mistakes that shrink a home insurance payout
Most underpaid and denied home claims trace to a short list of avoidable errors. Watch for these:
- Cleaning up before recording. Pulling out drywall and hauling ruined belongings to the curb before you photograph and inventory them is the most expensive mistake, because an assessment can only value damage that can still be verified.
- Filing a small claim that costs more than it pays. A claim that barely clears your deductible recovers little but can affect your renewal premium for years, as our claim-and-premium note explains. Weigh whether to file at all, and read our note on lowering your premium for the levers that do not involve a claim.
- Trusting a deadline you read somewhere. Notice duties, documentation schedules, and limits on bringing suit all vary by policy and by state. Get yours confirmed in writing by your insurer and calendar them the day you report.
- Accepting the first offer without checking it. On a replacement-cost policy the first payment is often the actual cash value rather than the full amount, and the estimate may be short on scope or measurements. Compare it against your own line-item bids first.
- Under-recording contents. A thin belongings list with no ages, models, or values is the quiet reason contents payments come in light, particularly where contents are valued at actual cash value.
- Skipping protective work. Failing to cover, dry, or shut off lets damage spread, and the insurer can treat the added loss as preventable. Protect the property promptly, but keep the work temporary until the inspection.
- Forgetting the living-expenses side. Hotel nights, meals out, and extra travel while the home is unusable are a separate coverage that goes unclaimed constantly because nobody kept the receipts.
- Handling everything by phone. Verbal agreements evaporate. Confirm anything that matters by email, and keep a dated log of every call.
Troubleshooting: when the claim does not go smoothly
What if my claim is denied? Read the denial letter for the stated reason, because it points to the fix. If the insurer attributed the damage to gradual wear, neglect, or an excluded cause rather than a sudden covered event, gather evidence that ties it to the covered event, meaning photographs, dates, weather records for the day, and contractor opinions on cause, then appeal in writing with a clear rebuttal. Our appeal walkthrough covers the sequence. Your state department of insurance handles complaints about claim handling, and for a large loss a public adjuster or an attorney experienced in coverage disputes may help. Ask the insurer to confirm in writing what deadlines apply to a dispute.
What if the payout is too low? Compare the adjuster’s estimate line by line against your own contractor bids and your inventory. Short scope, short measurements, and heavy depreciation are the usual culprits, in that order. Submit the difference as a documented supplement rather than as a complaint about the total. And remember that on a replacement-cost policy part of the amount is commonly held back until repairs are completed and documented, so a light first payment may not be the final one.
What if the adjuster and my contractor disagree? That gap is normal and it is exactly what a supplement is for. Line the two estimates up item by item to see whether they differ on scope, on quantity, or on unit price, because each of those is argued differently. Scope gaps are answered with photographs, quantity gaps with measurements, and price gaps with local bids. Some policies also contain a formal process for resolving a disagreement about the amount of a covered loss; whether yours has one, and what it involves, is a question for your policy wording and your insurer rather than something to assume.
What if hidden damage turns up mid-repair? This is common, particularly with water. Stop, photograph the newly exposed damage before the contractor covers it again, and tell the adjuster in writing straight away. Newly discovered damage from the same event is normally handled as a supplement to the existing claim rather than as a new claim, but confirm that with your insurer before anyone proceeds.
Will filing raise my premium, and can I avoid it? It often can, because insurers price on claim history, though the size of any change depends on your insurer, your state, and the type of claim. You cannot un-file a claim, but you can avoid filing a small one that is not worth it, keep the record clean over time, and shop your coverage at renewal. Our claim-and-premium note walks the tradeoff, and every figure in it is illustrative.
Your home insurance claim checklist
Save this and work it top to bottom when a loss hits:
- Confirm everyone is safe; get out and call the utility if there are downed lines, gas, or structural danger.
- Take reasonable temporary steps to stop further damage, meaning cover, dry, and shut off, and keep the receipts.
- Photograph wide then close in every room, plus all four exterior elevations and the point of entry.
- Shoot narrated video room by room and back everything up to the cloud before you do anything else.
- Build an itemized inventory of belongings with ages, models, and rough values, kept separate from the structure list.
- Read your declarations page: deductible, limits, separate wind or hail deductible, and replacement cost versus actual cash value.
- Read the duties-after-loss section of your policy so you know what the insurer can ask of you.
- Decide whether the loss is worth filing given your deductible, before you call.
- Report the loss promptly, get a claim number, and get the documentation requirements and dates in writing.
- Calendar every date the insurer gives you on the day you receive it.
- Do not begin permanent repairs or discard items before the inspection.
- Get your own line-item contractor estimates and compare them against the adjuster's, item by item.
- Keep every receipt for hotel nights, meals, and travel while the home is unusable.
- Read the settlement as covered damage reduced by depreciation and deductible; supplement or appeal in writing if it comes up short.
The bottom line
Filing a home insurance claim is not complicated, but it is unforgiving about order. Keep everyone safe and stop further damage first, photograph and inventory everything before you clean up, read your policy and deductible before you call, report the loss promptly and get a claim number, work with the adjuster while gathering your own line-item estimates, and read the payout as covered damage reduced by depreciation and your deductible. Decide whether a small loss is even worth filing, keep the living-expense receipts, and supplement or appeal in writing if the offer comes up short.
Where this walkthrough deliberately stops is on the specifics only your own paperwork can answer: your deadlines, your limits, your settlement basis, and what your insurer will actually pay. Those live on your declarations page, in your adjuster’s written confirmations, and with your state department of insurance, and a number borrowed from a page that has never seen your policy is worse than no number at all. If outside water was involved, this is the wrong walkthrough and you want our flood-claim walkthrough instead; for the coverage picture behind it all, our note on what home insurance covers is the companion piece. When a loss does hit, run your own numbers through the companion below so you know the shape of the payout, and whether to file, before you pick up the phone.
Everything above is educational reading about how home insurance claims commonly work. It is not insurance, legal, or financial advice, it does not describe your policy, and it cannot tell you how your claim will be handled. Coverage, deductibles, settlement basis, depreciation, notice and documentation requirements, limitation periods, and appeal rights differ between insurers, between policy forms, and between states, and they change over time. Every dollar amount, percentage, share, and day count above is an illustrative example chosen to show how the mechanics fit together; none of them is a quote, a deadline you can rely on, or a prediction of what any insurer will pay. Whether a claim is worth filing, and what it does to your premium, depends on your own insurer and history. Before you act, read your declarations page and your full policy, follow the written instructions your insurer gives you on your own claim, check your state department of insurance for the consumer rules where you live, and consult a licensed insurance professional, a licensed public adjuster, or an attorney about your particular loss.
Frequently asked questions
How do I file a home insurance claim?
You start by making sure everyone is safe and taking reasonable steps to stop further damage, such as covering an opening in the roof or shutting off the water, because most policies ask you to protect the property from further loss. Before you clean up, photograph and video every damaged room, surface, and belonging, then report the loss to your insurer or agent and write down the claim number. An adjuster is typically assigned to inspect the damage and build an estimate, and you can get your own repair estimates from licensed contractors to compare against it. You then read the settlement as covered damage reduced by depreciation and your deductible, and you can supplement or appeal it in writing if it comes up short. Treat every figure and timeline in this walkthrough as illustrative and confirm the actual steps with your own insurer, because procedures differ by policy and by state.
How long do I have to file a home insurance claim?
There is no universal number, and any specific count of days you read online is somebody else's policy rather than yours. Homeowners policies generally impose a duty to give notice of a loss without unreasonable delay, they let the insurer request documentation on a schedule the insurer sets, and they cap how long you have to bring a lawsuit if you end up disputing the outcome. All three of those vary by insurer, by policy form, and by state law, and some states regulate them directly. The practical approach is to report within a day or two anyway, because delay lets damage spread and gives the insurer a reason to question the cause. Then ask your insurer, in writing, for the exact dates that apply to your claim, put them on a calendar the day you get them, and check your state department of insurance for the consumer rules in your state.
Will filing a home insurance claim raise my premium?
It often can, because insurers price partly on claim history, and a paid claim can follow you to renewal and stay visible to insurers for some years through shared claims reporting. How much it moves is not something anyone can quote you in advance, because it depends on your insurer's rating plan, your state's rules, the cause and size of the loss, and how many claims you have filed recently. Water damage and liability claims tend to weigh more heavily in many rating plans than a single weather event, though that is a general pattern rather than a rule you can rely on. This is the reason a small claim that barely clears your deductible is often not worth filing. Our note on how a claim can affect your premium walks the tradeoff, and every figure in it is illustrative rather than a quote.
What is the difference between replacement cost and actual cash value on a claim?
Replacement cost, often written RCV, is what it would cost to repair or replace the damaged property with materials of like kind and quality, before any deduction for age. Actual cash value, or ACV, is that replacement cost reduced for wear and age, so a fifteen-year-old roof is valued as a fifteen-year-old roof rather than a new one. The difference between the two is the depreciation. On many replacement-cost policies the insurer pays the actual cash value first and holds the depreciation back until the repairs are actually completed and documented, which is why a first check can look light without being the final number. On an actual cash value policy there is nothing held back to recover, so the smaller amount is the whole amount. Read your declarations page to see which basis applies to your dwelling and to your contents, since the two can differ, and treat any percentage here as illustrative.
What does a home insurance adjuster do, and can I get my own estimate?
The adjuster inspects the damage, measures and photographs it, works out what caused it, and builds a repair estimate that the insurer uses to shape its offer. The adjuster is paid by the insurance company rather than by you, which does not make them hostile, but it does mean the estimate reflects the insurer's scope assumptions and its pricing data. You can get your own written estimates from licensed contractors, and doing so is the most reliable way to test whether the insurer's number matches the real scope and local labor and material costs. You can also point out damage the inspection may not reach, such as water behind a wall, under flooring, or in the attic. If the two estimates differ materially, that documented gap is what a supplement is built on.
What should I photograph before I call my insurer?
Shoot wide first and close second. Start with a wide shot of every affected room from the doorway so the whole space is established, then move in on each specific point of damage: the stained ceiling, the buckled floorboards, the broken window, the ruined furniture. Photograph the outside of the home and, if you can do it safely from the ground, the point where the damage came in, because that is what ties the loss to a sudden event rather than to gradual wear. Capture model and serial plates on damaged appliances and electronics while they are still readable, and photograph each significant belonging next to its wider room shot. Shoot video as well, narrating what the camera is seeing. Photograph any temporary protective work you did and the receipts for it, then keep the originals rather than only the compressed copies you send.
Is it worth filing a home insurance claim for minor damage?
Often it is not, and this is one of the more useful judgment calls in owning a policy. If the repair cost is close to your deductible, you may recover very little after the deductible comes off, while still adding a claim to a record that can affect your premium at renewal and for some years after. The rough test many people use is whether the damage exceeds the deductible by enough to be worth the future cost, which is a personal calculation rather than a fixed threshold. Large losses, structural damage, and anything involving injury to someone else sit in a different category and are usually worth reporting. Run your own damage figure and deductible through the companion below to see the illustrative payout, then weigh it against the premium effect described in our claim-and-premium note.
What if my home insurance claim is denied or the offer is too low?
Read the denial or the estimate closely first, because the stated reason tells you what evidence to gather: a cause the insurer treats as excluded, damage attributed to wear or neglect rather than a sudden event, or a repair scope narrower than the real damage. Answer that specific reason with your photographs, independent contractor estimates, and a written explanation of exactly where you disagree, and submit it as a supplement or a formal appeal. Keep copies of everything, because a disputed claim is argued on paper rather than on the phone. Every state has a department of insurance that handles consumer complaints about claim handling, and for a large or complex loss a licensed public adjuster or an attorney experienced in coverage disputes may be worth the fee. Ask your insurer to confirm in writing what deadlines apply to your dispute, and calendar them, because informal negotiation can run past them.
Does home insurance cover water damage, and how is that claim different?
It depends on where the water came from, which is the single most contested question in home claims. A sudden and accidental event, such as a pipe bursting or an appliance overflowing, is commonly covered, while gradual leaks, seepage, and long-term wear are typically treated as maintenance rather than a covered loss, and flood, meaning rising surface water from outside, is excluded from standard homeowners policies and needs a separate flood policy. That distinction changes how you document a water claim: you want evidence that the event was sudden and that you moved quickly to stop it. Our coverage note on water damage walks exactly where that line falls, and our separate flood-claim walkthrough covers the process when the water came from outside. Confirm the specific cause with your insurer, because the same puddle can be a covered claim or an excluded one depending on its source.
Hamza Hai is the editor of SumSured. She holds an MBA and reviews the site's articles against our editorial standards, checking that every figure is labelled for what it is, that nothing is presented as verified fact without a source the reader can check, and that the writing stays useful to a non-specialist.